HRP Financial
๐ŸŒพ Texas Ag Wealth Protection

Protect Your Ranch Heritage Before the 2026 Rollback Clock Hits

The only fourth-generation rancher licensed to protect your family's agricultural heritage โ€” now helping Texas landowners calculate their rollback tax exposure before it's too late.

โœ“ Licensed TX, CA, NV, MT, UT, NM โœ“ 4th-Generation Rancher โœ“ Strategic Partnership Session โœ“ High Plains Based
Your Quick Exposure Snapshot
3
Year rollback window
5%
Interest per year owed
$7M
2026 estate tax threshold
4th
Generation Kyle represents
3 Years
Rollback Window (reduced from 5 in 2019)
$0 Floor
Ag Appraised Value Protection Possible
4th Gen
Kyle's Ranching Background
Dec 31
TCJA Sunset Deadline โ€” 2025
๐Ÿงฎ Primary Tool โ€” 2026 Estimator

2026 Texas Ag Rollback Tax Estimator

In Texas, land appraised under the 1-d-1 agricultural exemption is taxed on productivity value โ€” often $50โ€“$200/acre โ€” rather than market value. If that status is lost, the county collects back-taxes on the full difference for the past 3 years, plus 5% interest per year. Find out your exposure in 60 seconds.

Enter Your Land Details
200 acres
Drag to your approximate total ag acreage
$3,500/acre
Current fair market value per acre (not ag appraised value)
$100/acre
Your current 1-d-1 productivity appraisal (check your CAD notice)
1.85%
County + ISD + special district combined levy rate. See county reference below.
Methodology: Annual savings = Acres ร— (Market โˆ’ Ag Value) ร— Tax Rate. Rollback = 3 years of savings + 30% interest (5%/yr ร— 3 years compounded). Results are estimates; consult your county appraisal district for binding figures.
Your Rollback Exposure Estimate
Annual Tax Savings (Current) $12,155
3-Year Rollback Base $36,465
Interest Charges (5%/yr ร— 3 yrs) $3,647
โš ๏ธ Total Rollback Exposure
$40,112
$200/acre exposure
ELEVATED RISK Estate planning review recommended

Results update live as you adjust sliders. Share your exposure number with your estate attorney and financial advisor. Kyle offers a complimentary ranch heritage partnership session.

Schedule Strategic Partnership Session
๐Ÿ“‹
Your Free Texas Ranch Heritage Protection Guide
Based on your rollback exposure, here's what to request in your free guide:
  • The 3 legal strategies to restructure land ownership before a rollback trigger
  • Texas 1-d-1 appraisal defense checklist (county-by-county)
  • Ag succession planning: how to pass the ranch without triggering estate taxes
  • How to layer asset protection with life insurance trusts on agricultural property

No spam. Unsubscribe anytime. Your data stays private.

โœ…
Guide sent! Check your inbox.
Kyle's team will follow up within one business day.

โš ๏ธ Based on your exposure, Kyle recommends scheduling a strategy call this week.

Schedule Strategic Partnership Session โ†’
โœ… Risk Assessment Tool

Texas 1-d-1 Ag Exemption Qualification Check

Most landowners don't know they're at risk of losing their exemption. Answer 8 questions to find out your vulnerability score โ€” and what to do about it.

Answer 8 Quick Questions
1. Is your land currently appraised under 1-d-1 agricultural appraisal?
2. Has agricultural activity been continuous for the past 5+ years?
3. Do you have records proving agricultural income or use?
4. Is your primary land use livestock, crops, or timber โ€” not residential?
5. Did you inherit this land and continue ag operations?
6. Do you have a clear succession plan if you or a co-owner passes?
7. Is your entity structure (LLC/trust) properly documented with the county?
8. Have you reviewed your appraisal district records in the past 12 months?
Your Exemption Security Score
โ€”
Answer questions to see your score
Your score will appear here as you answer each question above.
048

Get Your Personalized Ag Exemption Action Plan

Kyle will review your score and send a custom checklist of the exact steps to shore up your 1-d-1 protection before year-end.

โœ… Action plan sent! Check your email.
Why this matters: Texas counties audit ag exemptions regularly. Missing documentation โ€” especially after an ownership transfer โ€” is the #1 reason families lose their 1-d-1 status and face unexpected rollback bills.
Reference Data โ€” 2025 Tax Rates

2025 Texas County Agricultural Tax Rate Reference

Combined county + ISD + special district rates for agricultural land in the Texas Panhandle and High Plains. Use these to calibrate the rollback calculator above.

Potter County2.15%
Randall County1.89%
Moore County1.72%
Gray County1.65%
Carson County1.78%
Deaf Smith County1.58%
Hemphill County1.45%
Lipscomb County1.38%
Ochiltree County1.52%
Roberts County1.29%
Donley County1.61%
Collingsworth County1.55%
Wheeler County1.63%
Oldham County1.41%
Hartley County1.49%
Sherman County1.35%
Disclaimer: Rates shown are approximate combined levy rates derived from 2024 appraisal district records and public CAD data. Rates fluctuate annually based on certified taxable value changes and school finance formulas. Always verify the current certified rate with your county appraisal district before making financial or legal decisions.
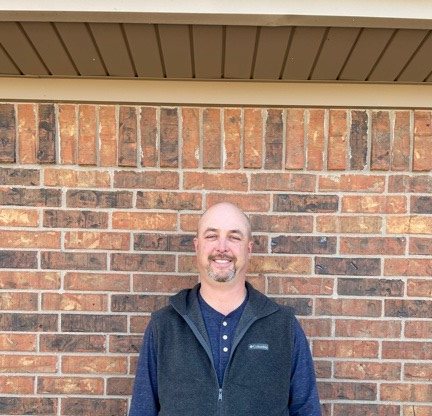
Kyle Ellison โ€” 4th Generation Rancher and HRP Financial Founder
The Rancher Behind the Advisor

Why a Fourth-Generation Rancher Became a Financial Advisor

I grew up on the High Plains of Texas, where the land isn't just an asset โ€” it's the family's name, legacy, and livelihood rolled into one. My family has worked this ground for four generations. I know what it means to rise before daylight to tend cattle in a Texas Panhandle winter, and I know exactly what's at stake when an ag exemption slips through someone's fingers because the paperwork wasn't right.

"I watched neighbors lose their ag appraisal status after a property transfer and face a tax bill that nearly wiped out what their grandfather built. That's not just a financial problem โ€” it's a generational tragedy. That's why I got licensed."

After years of ranching and watching too many families navigate land transitions without the right guidance, I pursued my insurance licenses to combine what I know on the ground with the financial tools that actually protect it. Kyle works with carriers who offer permanent protection products with a $0 guaranteed floor โ€” meaning the ranch family's protection doesn't evaporate when cattle prices drop or markets turn. That's the kind of certainty a ranch family can build a succession plan around.

The families who work with Kyle are running operations where the decisions matter โ€” payroll, succession, land, livestock, the next generation. The conversation has to match that reality. That is the conversation Kyle is built for.

Schedule Strategic Partnership Session โ†’
Common Questions

Texas Ag Exemption & Rollback Tax FAQ

Straight answers about Texas agricultural appraisals, rollback tax triggers, and ranch estate planning.

What triggers a rollback tax in Texas?
A Texas ag rollback tax is triggered when land that has been receiving the 1-d-1 agricultural appraisal changes to a non-agricultural use. Common triggers include selling to a developer, constructing a residence on the property, subdividing the land, or allowing agricultural activity to cease for a period that fails to meet the county's eligibility requirements. The tax is assessed the moment the change in use is reported to or discovered by the county appraisal district. Even a brief lapse in documented agricultural use โ€” such as a year where no grazing or crop production occurred โ€” can be grounds for the county to remove the exemption and assess the rollback retroactively.
How long is the Texas ag rollback period?
Since Senate Bill 1943 took effect on January 1, 2020, the Texas ag rollback period is 3 years โ€” reduced from the previous 5-year window. Each of those 3 prior years carries a 5% simple interest charge on the back-taxes owed. That means year 1 carries 15% cumulative interest added, year 2 carries 10%, and year 3 carries 5%, for a combined interest load of 30% of your annual tax savings multiplied by three. For a 500-acre tract with significant market-to-ag value spread, this can easily total $40,000โ€“$200,000 in unexpected liability.
Can I avoid rollback tax by selling to another ag user?
Selling to a buyer who continues agricultural use does not automatically trigger a rollback tax. If the new owner maintains the land in qualifying agricultural production and applies for โ€” and receives โ€” the 1-d-1 appraisal from the county, the rollback clock does not reset. However, if there is any gap in continuous ag use during the transition, or if the county determines the new owner failed to file timely, a rollback can still be assessed against the estate. Proper buyer due diligence and an attorney-reviewed sales agreement with explicit representations about ag use continuation are essential to protecting both parties.
What is the 1-d-1 agricultural appraisal in Texas?
The 1-d-1 appraisal (named for Article VIII, Section 1-d-1 of the Texas Constitution) is the primary agricultural use valuation in Texas. Rather than being taxed on market value, qualifying land is appraised at its productivity value โ€” essentially what the land can generate through grazing, crops, or timber. In the Texas Panhandle and High Plains, this often means land appraised at $50โ€“$200 per acre rather than the $2,000โ€“$10,000 market range, creating substantial annual tax savings. The downside is that those savings create a corresponding rollback liability that follows the land until the exemption is well-established and the ownership is stable.
How do I calculate my ag rollback tax?
Multiply your total acres by the difference between the market value per acre and the agricultural appraised value per acre. Then multiply that result by your combined county tax rate to get your annual tax savings. The rollback base is three times that annual savings amount. Add interest of 5% per year on each of the three prior years โ€” effectively 5% ร— 3 = 15% on year 1's savings, 5% ร— 2 = 10% on year 2's savings, and 5% ร— 1 = 5% on year 3's savings โ€” for a total interest charge of 30% of annual savings. Use the calculator at the top of this page to run your numbers in real time based on your actual acreage, values, and county rate.
What happens to my ag exemption if I die?
Death itself does not trigger a rollback tax, but it frequently sets the chain of events in motion. If heirs inherit the property and do not continue qualified agricultural use, or if the estate is forced into a sale to cover estate taxes or probate costs, the rollback can be assessed against the estate. Worse, if heirs disagree about whether to keep the land or sell, the resulting uncertainty may cause agricultural use to lapse while the dispute is resolved. Proper estate planning โ€” including a clear succession plan, properly documented entity structure, and a testamentary trust or irrevocable land trust โ€” can preserve the ag appraisal across generations and avoid a forced liquidation scenario.
Can an LLC or trust maintain the ag exemption?
Yes, both LLCs and trusts can hold land and maintain the 1-d-1 agricultural appraisal in Texas, provided the entity conducts qualifying agricultural activity and the beneficial owners meet the eligibility requirements. The county appraisal district must be notified of the ownership structure, and annual reporting must reflect continuous ag use by the entity. Improperly documented transfers โ€” such as moving land into an LLC without notifying the appraisal district โ€” can inadvertently trigger a rollback. An attorney familiar with Texas appraisal law should review any entity restructuring involving ag land. Kyle works alongside ag land attorneys and can refer you to vetted legal counsel in the Panhandle region.
What is TCJA sunset and how does it affect Texas ranch estates?
The Tax Cuts and Jobs Act of 2017 (TCJA) roughly doubled the federal estate tax exemption โ€” to approximately $13.61 million per person ($27.22M for married couples) in 2025. That exemption is scheduled to sunset on December 31, 2025, reverting to approximately $7 million per person (indexed for inflation) beginning in 2026. For Texas ranch families, this is critical: a 500-acre High Plains tract at $5,000/acre carries $2.5M in land value alone. Add equipment, livestock, life insurance proceeds paid outside a trust, and retirement accounts โ€” and a family that was comfortably under the exemption in 2025 may be significantly exposed to a 40% estate tax on the amount over the threshold in 2026. Strategies like Irrevocable Life Insurance Trusts (ILITs), Grantor Retained Annuity Trusts (GRATs), and annual gift programs should be implemented before December 31, 2025.

Have a question not covered here? Kyle answers personally.

Call Kyle: (806) 683-3110
The HRP Family of Services

More Tools Across the HRP Network

Kyle's businesses work together to serve agricultural families, rural businesses, and heritage builders across the region.